



Impact Events

Sical Logistics Q2 FY27 Revenue Up 17.4% YoY to ₹1,055 Million
Sical Logistics Limited announced its unaudited consolidated financial results for the quarter and half-year ended September 30, 2026. The company reported a consolidated revenue of ₹1,055 Million for Q2 FY27, a 17.4% increase year-on-year. For the half-year ended H1 FY27, consolidated revenue reached ₹2,380 Million, up 27.1% YoY. The Terminals business benefited from the Chennai MMLP operations, while Warehousing & 3PL focused on operating discipline. The Mining Logistics business faced margin pressure due to monsoons and higher fuel costs but secured a significant ₹5,347 Million (including GST) contract over five years from Central Coalfields Limited (CCL) for overburden removal and coal extraction. The company expects H2 FY27 to be stronger with improved profitability and sustained growth across all businesses.

Aegis Logistics Approves QIP Floor Price of ₹1,161.85
Aegis Logistics Limited announced that its Fund Raising Committee has approved the floor price for a Qualified Institutions Placement (QIP) of equity shares. The floor price has been set at ₹1,161.85 per equity share, determined based on SEBI ICDR Regulations. The committee also approved the preliminary placement document and authorized the opening of the QIP issue on November 11, 2026. The company may offer a discount of up to 5% on the floor price. The 'relevant date' for price determination was fixed as November 11, 2026.

Great Eastern Shipping Company Ltd: No Buyback on Nov 11, 2026
Great Eastern Shipping Company Ltd has submitted its daily buyback report for November 11, 2026. According to the report filed with SEBI, the company did not buy back any equity shares on this date through its broker, Kotak Securities Limited. The cumulative number of shares bought back as of November 10, 2026, remains 45,33,444. The company has confirmed that these details will be available on its website and the stock exchange websites.

Hindustan Copper Board Approves Unaudited Financial Results
Hindustan Copper Limited (HCL) announced that its Board of Directors, in a meeting held on November 11, 2026, has considered and approved the Unaudited Financial Results (Standalone & Consolidated) for the quarter ended September 30, 2026. The results were prepared in accordance with Indian Accounting Standards 34 and reviewed by statutory auditors. The board meeting commenced at 4:00 PM and concluded at 8:00 PM.
Aditya Birla Money Board Meeting on Nov 14 to Consider Fund Raising
Aditya Birla Money Ltd has announced that its Board of Directors will convene on November 14, 2026, to discuss and approve a proposal for raising funds. In line with SEBI regulations, the company has closed its trading window for designated persons and their immediate relatives from November 14, 2026, until 48 hours after the board meeting concludes, i.e., up to November 16, 2026. This measure is to prevent potential insider trading.
Tera Software Board Approves Un-Audited Results, CFO Appointment, Preferential Issue
Tera Software Ltd announced the outcome of its Board of Directors meeting held on November 11, 2026. The board approved the un-audited standalone and consolidated financial results for the quarter and half-year ended September 30, 2026. Additionally, the company approved the appointment of Mr. G. Venkatanarayana as the new Chief Financial Officer (CFO) effective December 4, 2026. A proposal for a preferential issue of convertible warrants to the promoter group was also approved, subject to shareholder approval. The board also approved a change in the company's name and an alteration to the Memorandum of Association (MOA) to align with new business directions, both pending member approval. An Extra-Ordinary General Meeting (EGM) will be convened to seek shareholder approval for these proposals.
Aegis Logistics Approves Qualified Institutions Placement Floor Price
Aegis Logistics Limited's Fund Raising Committee met on November 11, 2026, to approve key aspects of a proposed Qualified Institutions Placement (QIP). The committee approved a floor price of ₹1,161.85 per equity share, determined based on SEBI ICDR Regulations. A preliminary placement document was also adopted, and the QIP issue was authorized to open on the same day. The company may offer a discount of up to 5% on the floor price. The 'relevant date' for price determination was fixed as November 11, 2026.
Sical Logistics Declares Unaudited Financial Results for Q2 FY27
Sical Logistics Limited announced its unaudited financial results for the quarter and half-year ended September 30, 2026. The Board of Directors approved these results, which were prepared in accordance with Indian Accounting Standard 34 and reviewed by statutory auditors CNGSN & Associates LLP. The results were also recommended by the Audit Committee. The company's website will host the information.
Shikhar Consultants Ltd Board Meeting on Nov 14, 2026
Shikhar Consultants Ltd has announced a Board of Directors meeting scheduled for November 14, 2026. The primary agenda item is to consider and approve the unaudited financial results for the quarter and half-year ended September 30, 2026, along with the limited review report. The trading window for company insiders will remain closed from October 1, 2026, until 48 hours after the results announcement.

Rain Industries Q3 2026 Management Commentary Released
Rain Industries Limited has released its management commentary on the un-audited financial results for the third quarter ended September 30, 2026. The commentary covers standalone, consolidated, and segment results. A link to the audio Q&A session and the transcript of the management commentary are provided. The discussion included topics such as near-term market conditions, strategic priorities, and balance-sheet management. Management also addressed competitive positioning in delivered costs and logistics amidst global smelting capacity expansions and discussed the impact of European regulations like CBAM on carbon costs.
Abans Financial Services Declares Unaudited Financial Results
Abans Financial Services Limited announced the approval of its Unaudited Financial Results (Standalone and Consolidated) for the quarter and half-year ended September 30, 2026, following a Board of Directors meeting held on November 11, 2026. A limited review report was also approved. The company also informed that the trading window for dealing in its securities will remain closed until 48 hours after the announcement, in compliance with insider trading regulations.
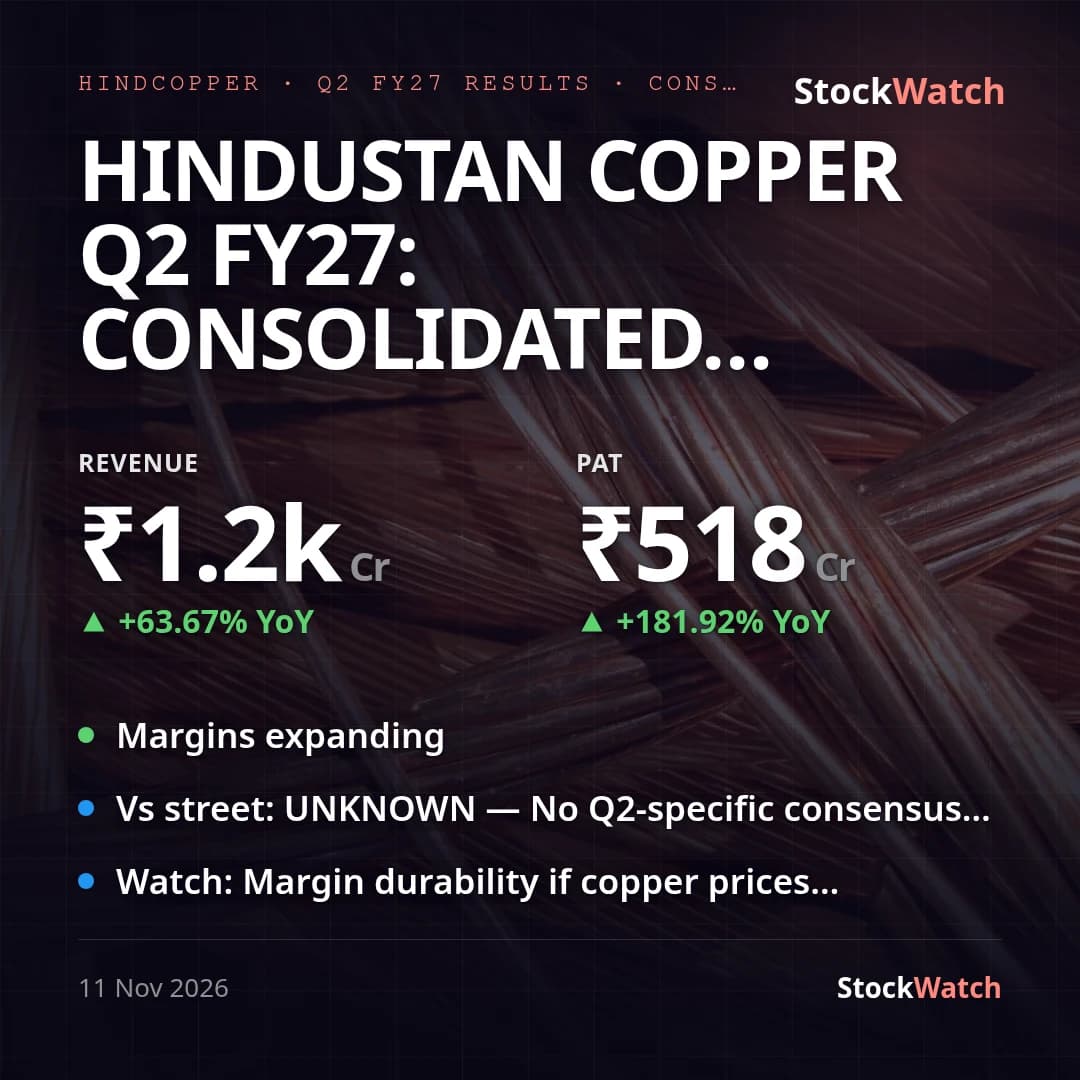
Hindustan Copper Q2 FY27: Consolidated PAT Soars 182% YoY to ₹518 Cr as Margins Expand
Hindustan Copper's consolidated net profit for Q2 FY27 (quarter ended September 30, 2026) came in at ₹518.13 Cr, up 182% year-on-year from ₹183.79 Cr in Q2 FY26, on revenue from operations of ₹1,175.24 Cr (+64% YoY from ₹718.04 Cr). Standalone (PAT ₹519.54 Cr, EPS ₹5.37) and consolidated (PAT ₹518.13 Cr, EPS ₹5.36) figures tell effectively the same story — the ₹1.41 Cr gap is just the company's share of loss from its Khanij Bidesh India joint venture, not a divergence in the underlying business. There were no exceptional items in either the current or year-ago quarter, so the growth is entirely organic rather than one-off-driven. Margins expanded on both axes: net profit margin (on total income) rose to 42.6%, from 36.95% in Q1 FY27 and 25.21% a year ago. The driver was operating leverage — total expenses grew just 8.0% quarter-on-quarter to ₹520.4 Cr while revenue grew 25.5% QoQ — against a backdrop of LME copper prices hitting repeated all-time highs (peaking near $14,858.50/t) in September 2026, lifting realizations on largely fixed mining costs. Against our pre-result preview, this is a decisive beat: we had flagged revenue of ₹850–950 Cr and PAT of ₹150–200 Cr going in; the actual print cleared both ranges comfortably (revenue ~24% above the top end, PAT over 2.5x the top end). We could not find a published sell-side consensus specific to this quarter's PAT or revenue; the closest data point is a full-year FY27 consensus of roughly ₹4,710 Cr revenue and ₹17.70 EPS, against which H1 FY27 revenue of ₹2,111.74 Cr and EPS of ₹9.00 are tracking close to half the full-year number with two quarters still to report. Notably, H1 FY27 consolidated PAT of ₹870.50 Cr already exceeds the ₹600 Cr full-year PAT figure used as an estimate in our preview. Management issued no formal outlook or guidance alongside this filing, so there is no company guidance to grade the print against. The quarter's board actions track the pre-result watch list: the flagged management transition played out, with the Executive Director (Operations) retiring on November 3, 2026, following new ED appointments at Mining-Production and Malanjkhand through September-October; a fresh appeal was filed in the Madhya Pradesh High Court on October 30, 2026 in the company's ongoing legal matter. We found no update in our event records on the 6% promoter OFS (₹514 floor) flagged pre-result. Capex execution continues to scale, with capital work-in-progress at ₹874.10 Cr (from ₹741.23 Cr at FY26-end) and H1 purchase of fixed assets of ₹242.70 Cr versus ₹52.12 Cr a year ago, consistent with the production-led expansion thesis our preview described.
Embassy Developments: Promoter Pledge Release & Re-creation for Lock-in
Embassy Developments Limited announced that its Promoter Group entities, Embassy Property Developments Private Limited (EPDPL) and OMR Investments LLP (OMR), have completed a transaction involving the release and subsequent re-creation of a pledge over 9,79,05,440 equity shares. This action, occurring between November 06, 2026, and November 11, 2026, was solely for regulatory compliance to meet lock-in requirements under ICDR Regulations following a preferential allotment of convertible warrants. The Promoter Group has converted all warrants, infusing approximately ₹362.62 crore into the company at ₹111.51 per share. This conversion has increased the Promoter Group's shareholding from 42.68% to 43.99%. The total number of pledged shares and underlying financing arrangements remain unchanged.

Regency Fincorp Ltd: Voting Results of 2nd EGM Held on Nov 11, 2026
Regency Fincorp Ltd has submitted the voting results for its 2nd Extra-ordinary General Meeting (EGM) held on November 11, 2026. The meeting, which lasted from 1:00 PM to 1:40 PM, saw 5 resolutions being passed. A key resolution involved increasing the company's authorized share capital and amending the Memorandum of Association. The voting results indicate strong support, with all resolutions passing with a high percentage of votes in favour, particularly from the promoter and promoter group, and public non-institutional shareholders. The total number of shareholders on the record date was 5737.
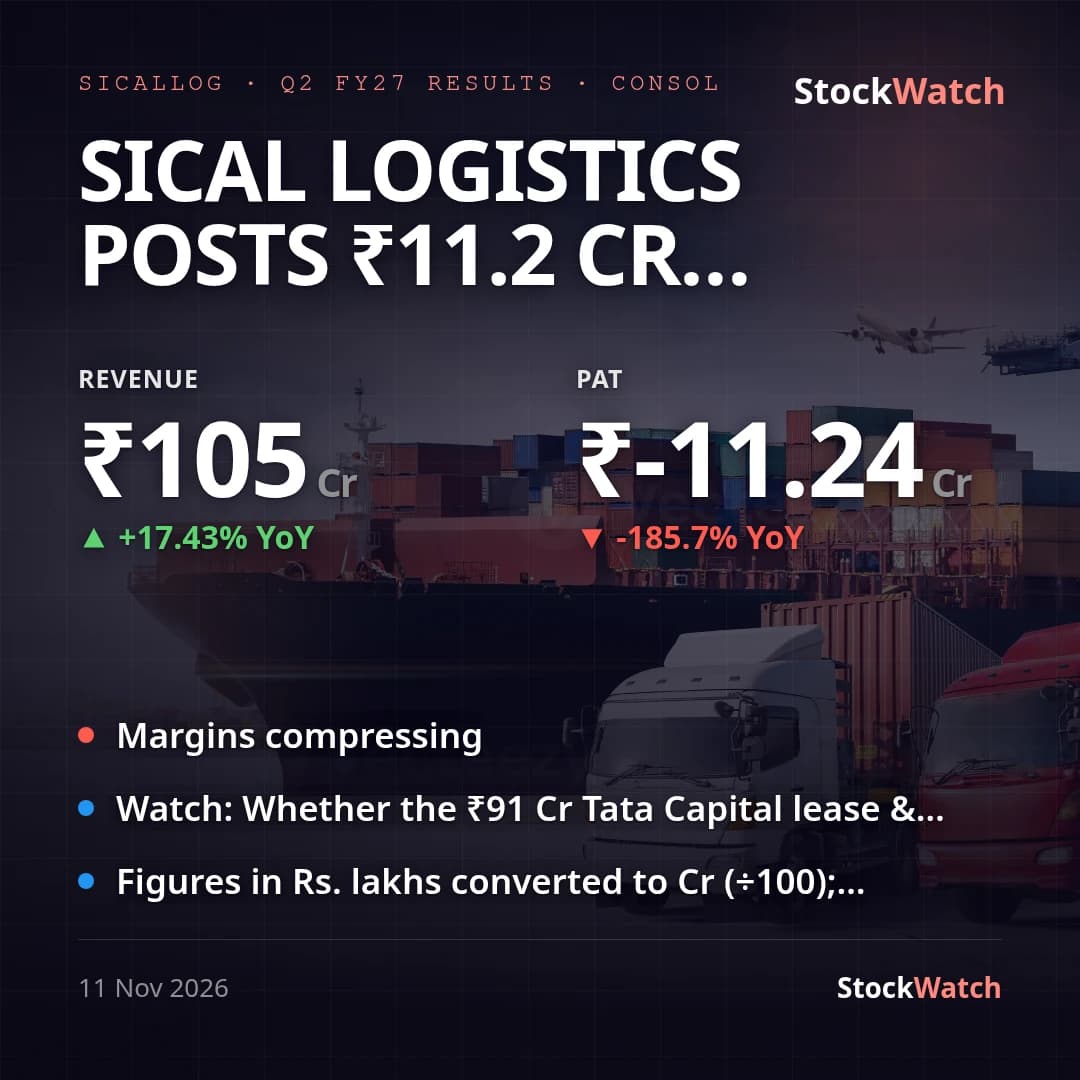
Sical Logistics posts ₹11.2 Cr consolidated loss in Q2 FY27 despite 17% revenue growth
Sical Logistics (consolidated, primary basis) swung to a net loss of ₹11.2 Cr in Q2 FY27 (owners' share -₹12.0 Cr, EPS -₹1.38) against a profit of ₹13.1 Cr a year ago (EPS ₹2.01) and ₹21.2 Cr last quarter (EPS ₹2.86), even as revenue from operations grew 17.4% YoY to ₹105.5 Cr — though it fell 20.5% QoQ from ₹132.6 Cr. The headline YoY swing is steeper than the underlying trend, however: Q2 FY26's reported profit was propped up by an outsized ₹29.6 Cr other-income line that closely matches a 'profit on sale of fixed assets' adjustment in the cash-flow statement — not classified as exceptional by the company. Stripping that out, last year's core pre-tax result was closer to a ₹15.6 Cr loss, meaning this quarter's ₹10.7 Cr core pre-tax loss is actually a roughly one-third narrower core loss YoY. The QoQ read cuts the other way: Q1 FY27's ₹21.2 Cr reported PAT included a disclosed ₹17.4 Cr exceptional gain, and even excluding it Q1's core PAT was still a positive ~₹3.8 Cr — so the slide into this quarter's ₹11.2 Cr loss reflects a genuine sequential deterioration in the core business, not just a one-off base effect. The pressure sits squarely on the cost line: consolidated total expenses rose 16.8% YoY to ₹123.1 Cr, with cost of services up roughly 40% YoY to ₹79.8 Cr — outrunning the 17.4% revenue growth and flipping operating profit into an operating loss. Balance-sheet data points to rising lease-driven costs as a contributor: right-of-use assets jumped to ₹116.4 Cr from ₹44.0 Cr at FY26-end and non-current lease liabilities rose to ₹89.2 Cr from ₹38.7 Cr, pushing up depreciation and finance charges even before the ₹91 Cr lease and working-capital facility the company signed with Tata Capital on October 27, 2026 — a post-quarter event that will likely add further finance cost from Q3 FY27. Standalone (secondary basis) posted a wider loss of ₹13.2 Cr (EPS -₹1.65) than the consolidated number, implying subsidiaries partly cushioned the holding company's losses this quarter. There is no management guidance or outlook on record for this company, and the print carries no formal press commentary beyond the standard Reg 30 board-outcome filing — so neither can be graded against this result. No analyst previews or consensus estimates for this specific quarter turned up in search, consistent with thin coverage (3 analysts per public trackers) on a small-cap name; vsStreet is marked unknown rather than assumed. Separately, the filing itself now carries 'A Pristine Group Company' branding, consistent with the October 2026 Pristine Logistics merger/share-acquisition events in the company's own record — a promoter-group change that sits alongside, but is not shown to have directly caused, this quarter's operating swing.